Commercial Property Insurance Quote Online: What Affects Premiums and Coverage Costs
Commercial Property Insurance Quote Online: What Affects Premiums and Coverage Costs sets the stage for this enthralling narrative, offering readers a glimpse into a story that is rich in detail and brimming with originality from the outset.
Exploring factors influencing insurance premiums, coverage options, online quoting processes, and strategies to lower costs, this guide is a comprehensive resource for navigating the complexities of commercial property insurance.
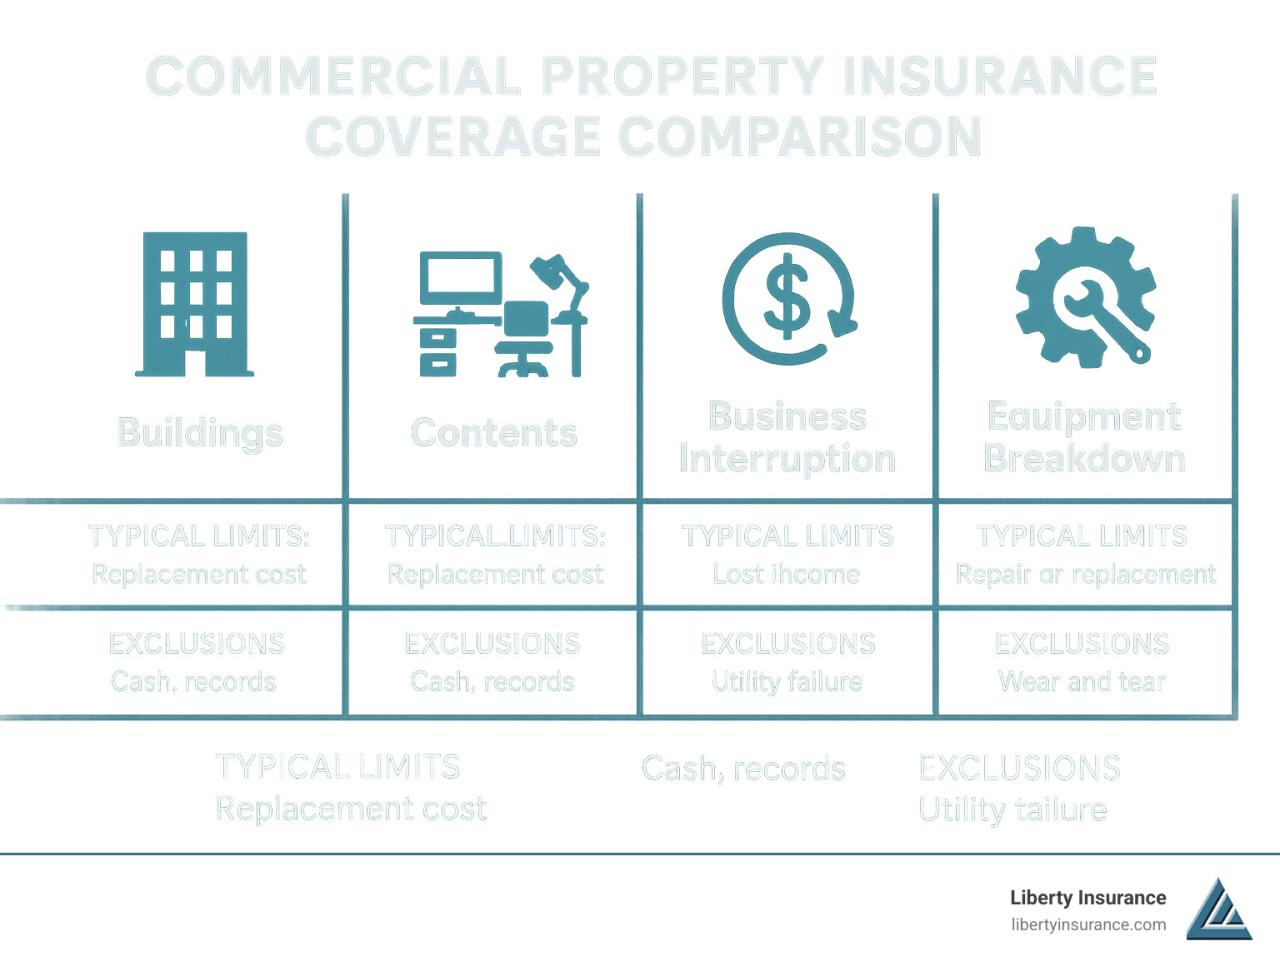
When it comes to commercial property insurance, several factors can influence the premiums you pay and the coverage you receive. Understanding these factors can help you make informed decisions about your insurance needs.
The location of your commercial property plays a significant role in determining your insurance costs. Properties located in high-risk areas, such as those prone to natural disasters or high crime rates, will generally have higher premiums. Insurers assess the risk associated with the location to determine the likelihood of claims.
The value of your property and its replacement cost are crucial factors in determining insurance premiums. Higher property values and replacement costs typically result in higher premiums since more expensive properties require a greater coverage amount in case of damage or loss.
The age and condition of the building on your commercial property can impact insurance rates. Older buildings may be more susceptible to structural issues or damage, leading to higher premiums. Regular maintenance and upgrades can help mitigate these risks and potentially lower insurance costs.
The type of business conducted on your commercial property can also influence insurance premiums. Businesses that involve higher risks, such as manufacturing or hazardous materials storage, may face higher premiums due to the increased likelihood of accidents or damage. Insurers consider the nature of your business activities when assessing the level of risk associated with your property.
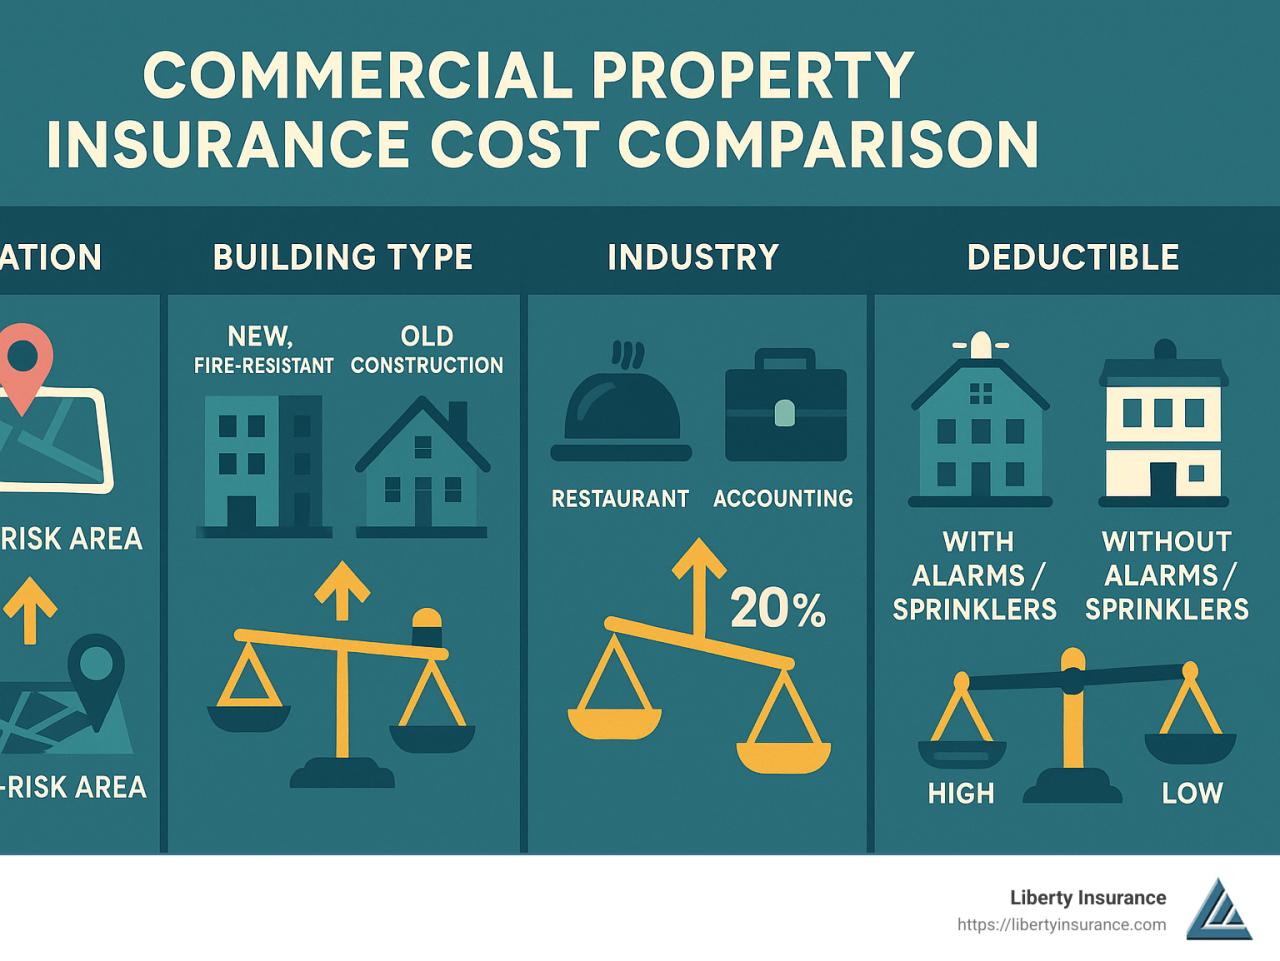
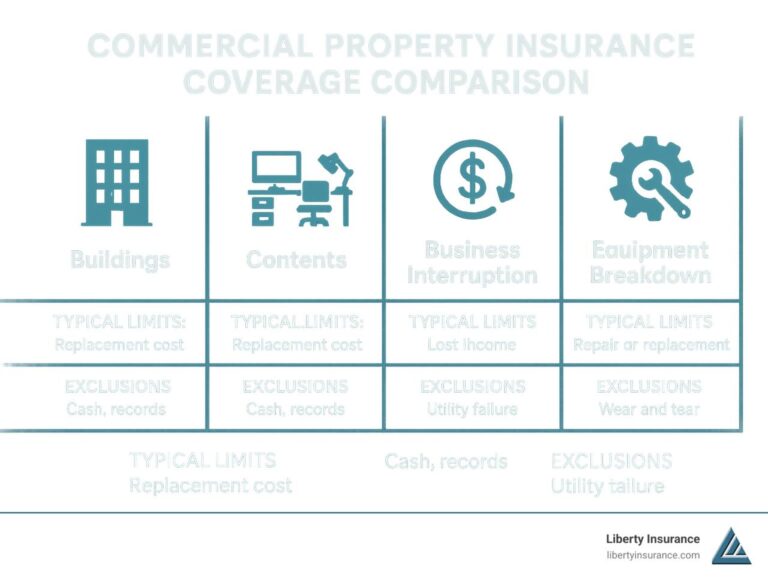
When it comes to commercial property insurance, there are different coverage options available to protect your business assets. Understanding the difference between basic coverage and additional riders can help you tailor a policy that meets your specific needs.
Basic coverage typically includes protection for your building and its contents against common risks such as fire, theft, vandalism, and natural disasters. Additional riders, on the other hand, offer extra coverage for specific risks that may not be included in a standard policy.
These riders can be added to provide coverage for things like equipment breakdown, sewer backup, or even terrorism.
Business interruption insurance is a crucial coverage option that can help your business stay afloat in the event of a disaster. This coverage can help replace lost income, pay ongoing expenses, and even cover the cost of temporary relocation if your business is forced to shut down due to a covered loss.
While adding business interruption insurance can increase your premiums, the protection it provides can be invaluable in keeping your business running smoothly.
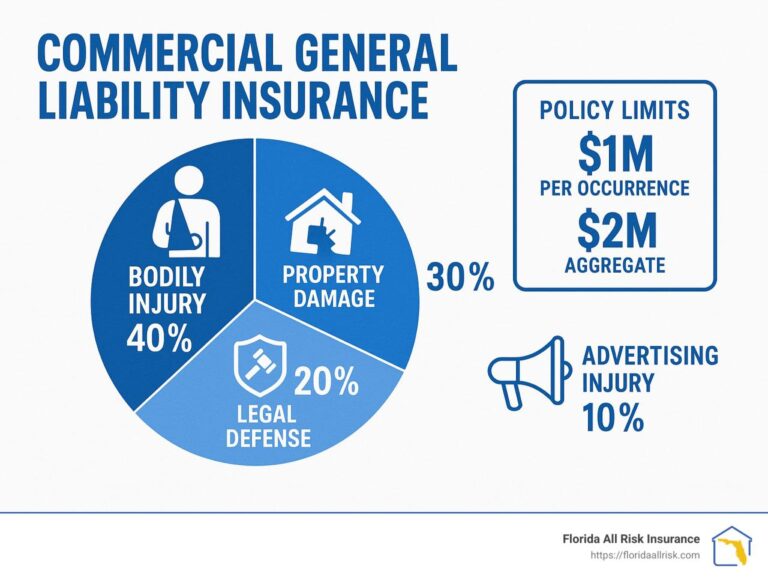
Liability coverage is essential for protecting your business from potential lawsuits and claims. This coverage can help pay for legal fees, settlements, and medical expenses if someone is injured on your property or as a result of your business operations.
Having adequate liability coverage can not only provide financial protection but also give you peace of mind knowing that your business is covered in case of unexpected events.
When it comes to obtaining a commercial property insurance quote online, there are specific steps involved that are crucial to ensuring you receive an accurate and competitive quote. Insurers utilize various risk factors to assess the level of risk associated with insuring a commercial property, which ultimately impacts the premium cost and coverage options available to you.
Providing accurate information during the online quoting process is essential to receiving a quote that aligns with your specific needs and requirements. Let’s delve into the details of the online quoting process for commercial property insurance.
When it comes to commercial property insurance, there are several strategies that can help lower your premiums and save you money in the long run.Improving Property Security:One effective way to reduce insurance costs is by improving the security of your property.
Installing security cameras, alarms, and sturdy locks can deter theft and vandalism, making your property less risky to insure. Insurance companies often offer discounts for properties with enhanced security measures in place.Bundling Options with Other Insurance Policies:Consider bundling your commercial property insurance with other insurance policies, such as general liability or business interruption insurance.
Insurance companies often provide discounts for customers who purchase multiple policies from them, helping you save money on overall premiums.Regular Maintenance and Risk Management Practices:Another way to lower your commercial property insurance premiums is by implementing regular maintenance and risk management practices.
By keeping your property well-maintained and addressing potential hazards promptly, you can reduce the likelihood of claims and demonstrate to insurers that you are a responsible policyholder.Impact of Deductible Choices:Choosing a higher deductible can also help lower your insurance premiums.
A deductible is the amount you agree to pay out of pocket before your insurance coverage kicks in. By opting for a higher deductible, you can lower your premiums, but it’s important to make sure you can afford the deductible in case you need to file a claim.
How does the location of the property impact insurance costs?
The location of the property can affect insurance costs due to varying risks associated with different areas, such as high crime rates or natural disaster susceptibility. Insurers consider these factors when determining premiums.
What is the role of business interruption insurance in coverage costs?
Business interruption insurance covers income loss when a business is unable to operate due to a covered event, such as a fire or natural disaster. It can impact coverage costs by providing financial support during downtime.
How can regular maintenance help lower insurance premiums?
Regular maintenance ensures the property is in good condition, reducing the risk of damage. Insurers view well-maintained properties as lower risk, potentially leading to lower premiums.