Commercial General Liability vs Professional Liability: Which Policy Does a Business Need?
Commercial General Liability vs Professional Liability: Which Policy Does a Business Need? sets the stage for this enthralling narrative, offering readers a glimpse into a story that is rich in detail with a casual formal language style and brimming with originality from the outset.
The discussion will delve into the key differences between these insurance policies, the types of risks covered, policy costs, and how businesses can determine the right policy for their needs.
When it comes to protecting your business, understanding the differences between Commercial General Liability (CGL) and Professional Liability insurance policies is crucial. Both types of insurance provide coverage for different types of risks that a business may face.
Commercial General Liability insurance typically covers claims related to bodily injury, property damage, and personal injury that occur on your business premises or as a result of your business operations. On the other hand, Professional Liability insurance, also known as Errors and Omissions (E&O) insurance, covers claims of negligence or failure to perform professional duties.
Commercial General Liability policies usually have coverage limits for each occurrence and an aggregate limit for the policy period. Professional Liability policies also have coverage limits but may include a deductible and coverage for legal defense costs. It’s important to note that both types of policies have exclusions, such as intentional acts or contractual liabilities, that may not be covered.
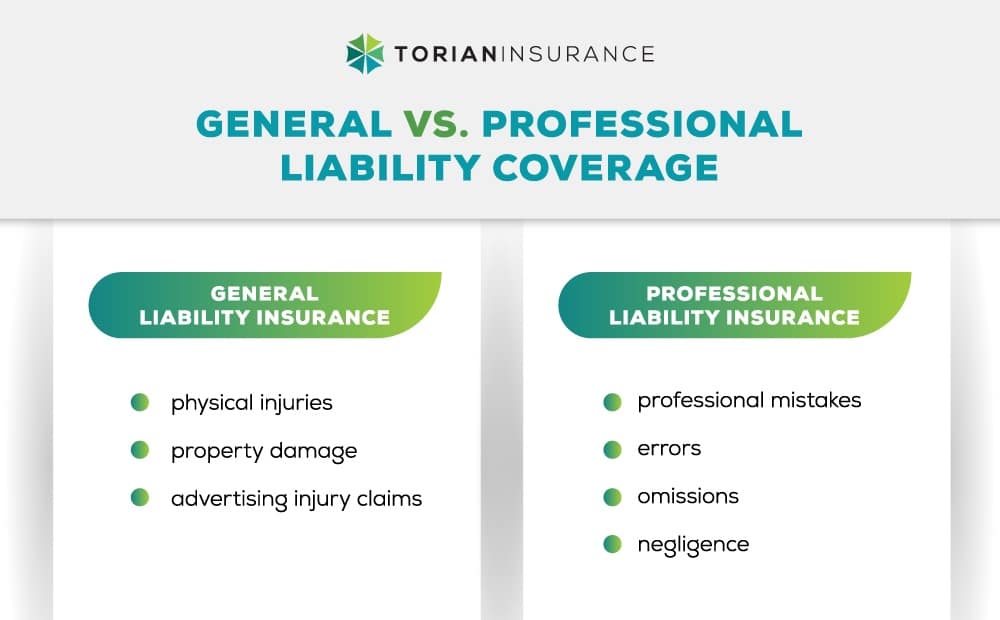
Commercial General Liability (CGL) insurance and Professional Liability insurance offer different types of coverage to protect businesses from various risks. Let’s delve into the specific types of risks covered by each policy.
Commercial General Liability insurance typically covers risks related to bodily injury, property damage, and advertising injury. This type of policy is designed to protect businesses from third-party claims of physical harm or property damage that occur on their premises or as a result of their operations.
Examples of claims covered under CGL insurance include slip-and-fall accidents in a store, damage caused by a contractor during a renovation project, or allegations of defamation in an advertisement.
Professional Liability insurance, also known as Errors and Omissions insurance, focuses on risks associated with professional services and advice provided by businesses. This type of policy covers claims of negligence, errors, or omissions that result in financial losses for clients.
Professionals such as doctors, lawyers, consultants, and architects often carry Professional Liability insurance to protect themselves from lawsuits stemming from mistakes in their work. Examples of claims covered under Professional Liability insurance include a doctor being sued for a misdiagnosis, a lawyer making errors in legal documentation, or a consultant providing faulty advice that leads to financial losses for a client.
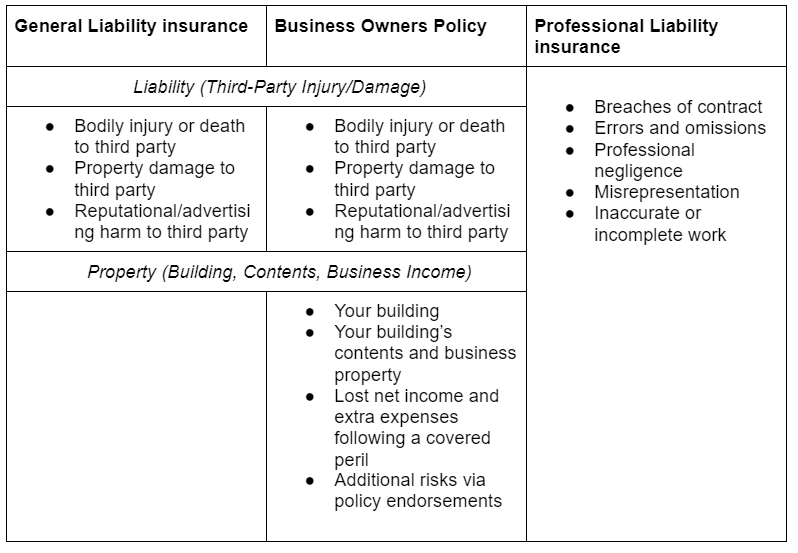
Commercial General Liability insurance and Professional Liability insurance are essential for protecting businesses from financial risks. However, the cost of these policies can vary based on several factors.
Commercial General Liability insurance and Professional Liability insurance are crucial for protecting businesses from various risks. Let’s explore which types of businesses typically require each policy and how businesses can determine which one suits their specific needs.
Commercial General Liability insurance is essential for businesses that interact with the public or have physical locations where customers can visit. Some types of businesses that typically require Commercial General Liability insurance include:
Professional Liability insurance, also known as Errors and Omissions insurance, is crucial for businesses that provide professional services or advice. Some professions or industries that often need Professional Liability insurance include:
Businesses can determine which policy suits their specific needs by assessing the nature of their operations and the risks they face. Consider the following factors:
What are the key differences between Commercial General Liability and Professional Liability insurance?
Commercial General Liability covers bodily injury and property damage claims, while Professional Liability covers claims related to professional services.
What types of businesses typically require Commercial General Liability insurance?
Businesses that have physical locations or face risks of customer injury should consider Commercial General Liability insurance.
How are premiums for Professional Liability insurance calculated?
Premiums for Professional Liability insurance are usually based on the type of profession, coverage limits, and claims history.
How can businesses lower their insurance costs for both types of policies?
Businesses can lower costs by implementing risk management strategies, maintaining a clean claims history, and comparing quotes from multiple insurers.