Commercial Personal Property Insurance: What Business Contents Coverage Includes
Commercial Personal Property Insurance: What Business Contents Coverage Includes sets the stage for this enthralling narrative, offering readers a glimpse into a story that is rich in detail and brimming with originality from the outset.
As we delve into the intricacies of commercial personal property insurance and business contents coverage, a world of protection and coverage unfolds.
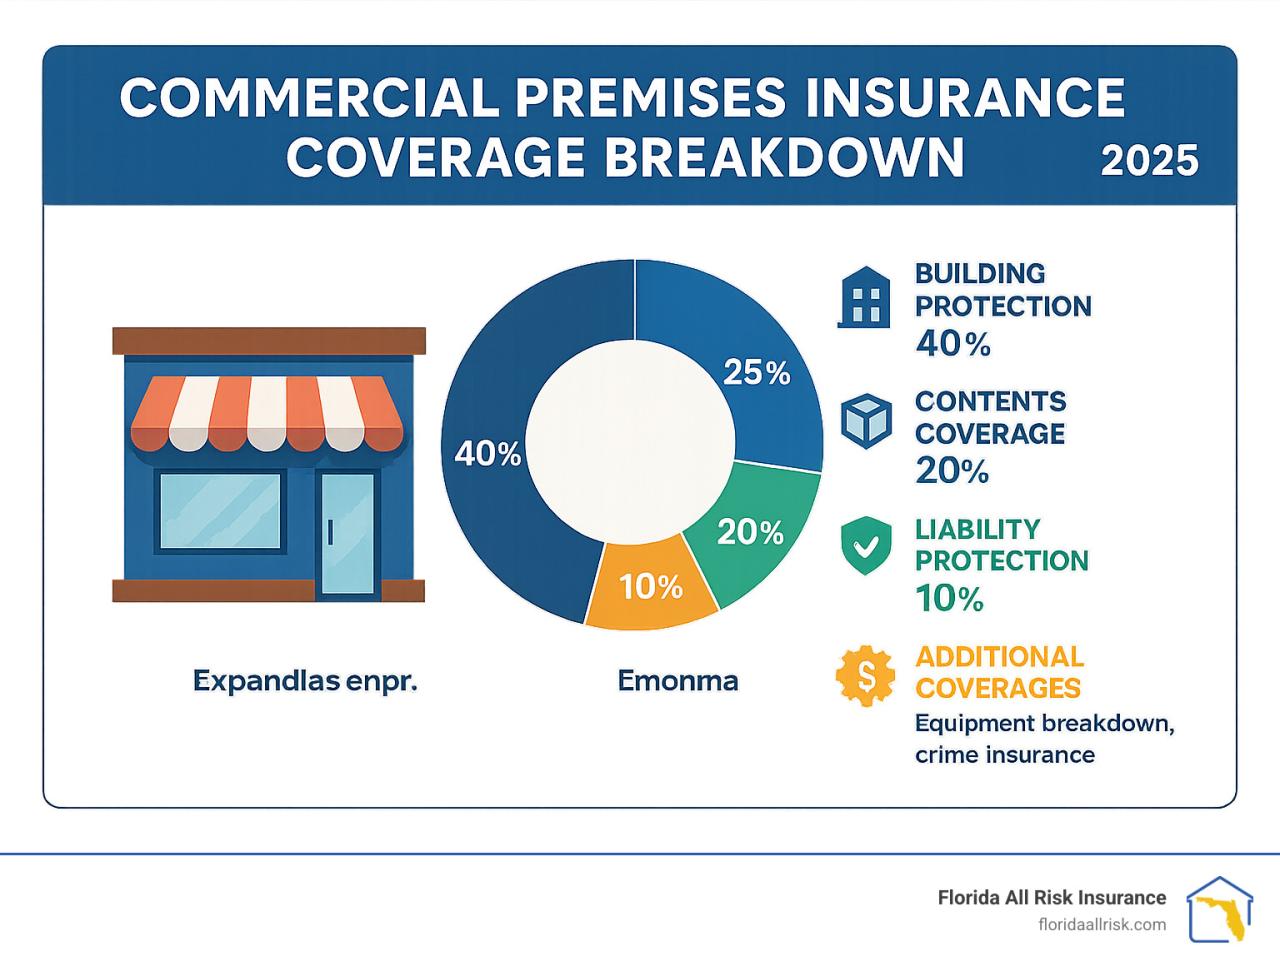
Commercial personal property insurance is a type of insurance that provides coverage for the physical assets of a business, such as equipment, inventory, furniture, and fixtures. It is essential for businesses to protect their valuable assets from unexpected events like theft, fire, or natural disasters.
Commercial personal property insurance primarily covers physical assets owned by the business, while general liability insurance protects against claims of bodily injury or property damage caused by the business operations. While both types of insurance are important for businesses, they serve different purposes in terms of protection and coverage.
When it comes to commercial personal property insurance, business contents coverage plays a crucial role in protecting a business’s assets and inventory in case of unexpected events like theft, fire, or natural disasters.
Business contents coverage typically includes items such as furniture, equipment, inventory, fixtures, and other tangible assets that are essential for the operation of the business. These items are usually located within the business premises and are vital for the day-to-day operations of the business.
The coverage amount for business contents is usually determined based on the value of the items at risk. This can be calculated by taking into account factors such as the replacement cost of the items, the age and condition of the items, and any depreciation that may apply.
It’s essential for businesses to accurately assess the value of their contents to ensure they have adequate coverage in the event of a loss.
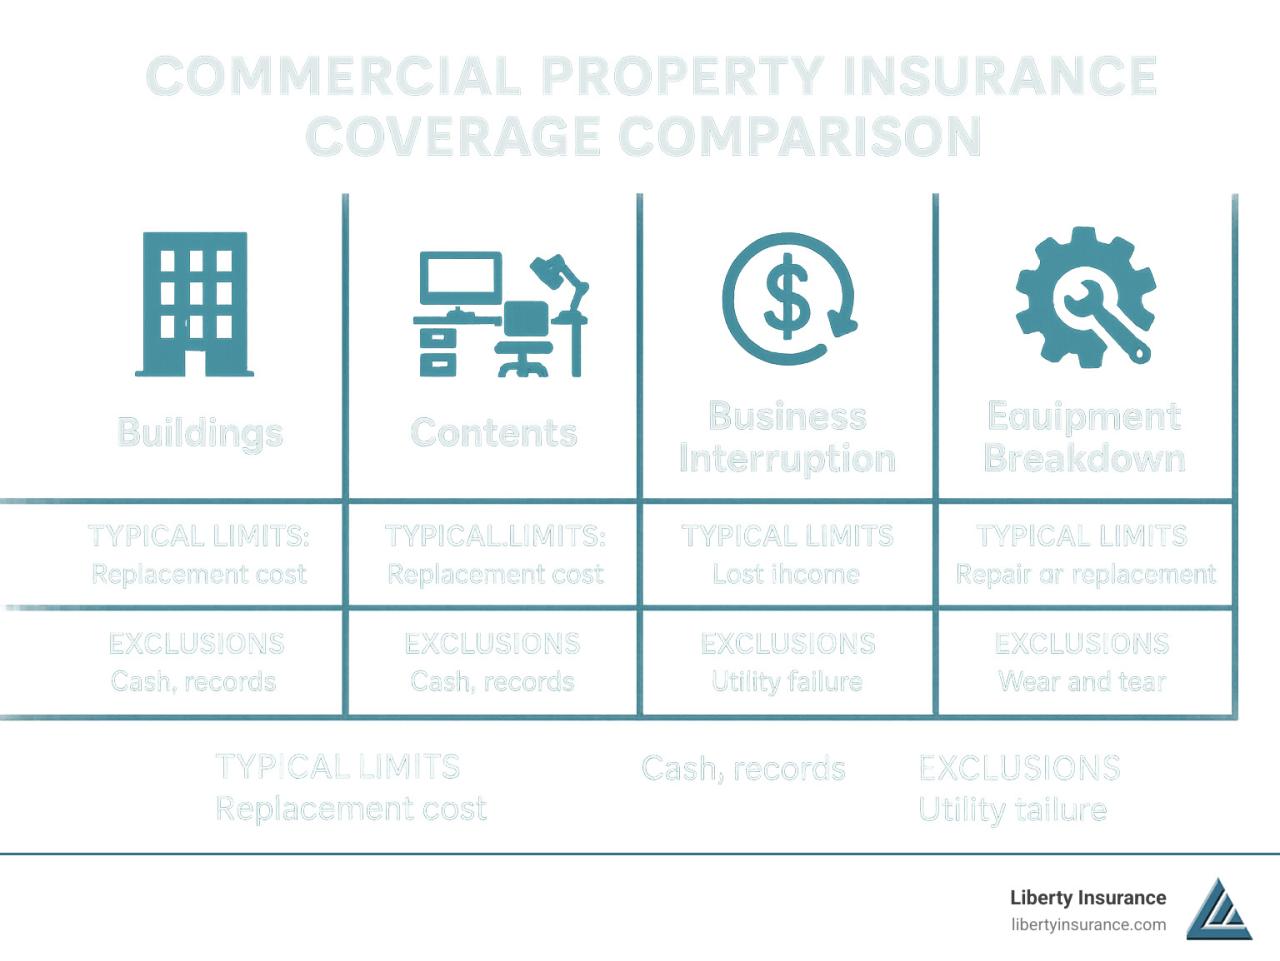
When it comes to business contents coverage, it is essential to be aware of the exclusions that may apply to your policy. Understanding these exclusions can prevent any surprises or misunderstandings in the event of a claim.
It is crucial to carefully review the exclusions in your commercial personal property insurance policy to ensure that you have the appropriate coverage for your business needs. By understanding what is not covered, you can make informed decisions about additional coverage options or risk management strategies to protect your business assets effectively.
When it comes to commercial personal property insurance, businesses have the option to enhance their coverage by considering additional options tailored to their specific needs.
Businesses can choose to add endorsements or riders to their commercial property insurance policy to extend coverage beyond the standard limits. These additional options provide extra protection for valuable items that may not be fully covered under a basic policy.
Businesses can customize their commercial personal property insurance by tailoring coverage options to meet their unique needs. This ensures that they are adequately protected against risks that are specific to their industry or location.
By selecting the right combination of endorsements, riders, and policy limits, businesses can create a comprehensive insurance package that addresses their individual requirements.
What does business contents coverage include?
Business contents coverage typically includes items like equipment, inventory, and furniture that are essential for business operations.
Are intangible assets covered under commercial personal property insurance?
No, commercial personal property insurance usually covers tangible assets like equipment and inventory, not intangible assets like intellectual property.
Can businesses customize their coverage under commercial personal property insurance?
Yes, businesses can often customize their coverage by adding endorsements or riders to enhance protection for specific items or scenarios.
Is loss due to natural disasters typically covered under business contents coverage?
It depends on the policy, but some business contents coverage may include protection against natural disasters like floods or earthquakes.