General Business Liability Policy: Coverage Limits, Exclusions, and Costs
As General Business Liability Policy: Coverage Limits, Exclusions, and Costs takes center stage, this opening passage beckons readers with an engaging insight into the essential aspects of this vital insurance coverage. Exploring the intricacies of coverage limits, common exclusions, and associated costs, this piece offers a comprehensive view of what businesses need to know to protect themselves effectively.
Delving into the specifics of coverage limits, policy exclusions, and financial considerations, this guide serves as a valuable resource for businesses seeking clarity on their insurance needs.
A General Business Liability Policy is a type of insurance that provides coverage for a business in case of claims related to bodily injury, property damage, and other liabilities. It helps protect businesses from financial losses resulting from lawsuits, medical expenses, or property damage claims.
Having a General Business Liability Policy is crucial for businesses of all sizes as it helps mitigate the risks associated with everyday operations. Without this insurance, a business may be vulnerable to expensive legal fees, settlements, or judgments that could potentially bankrupt the company.
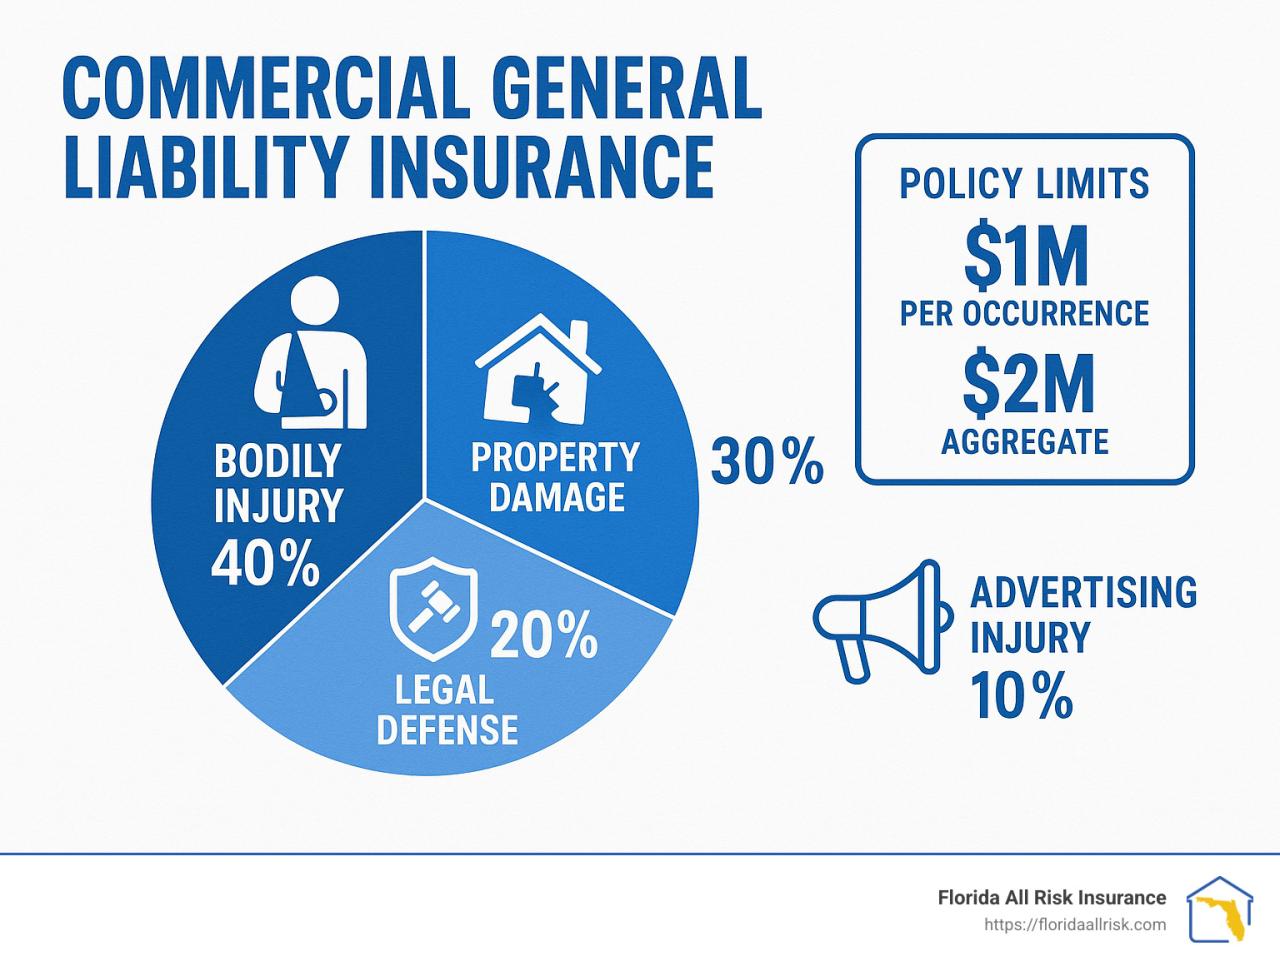
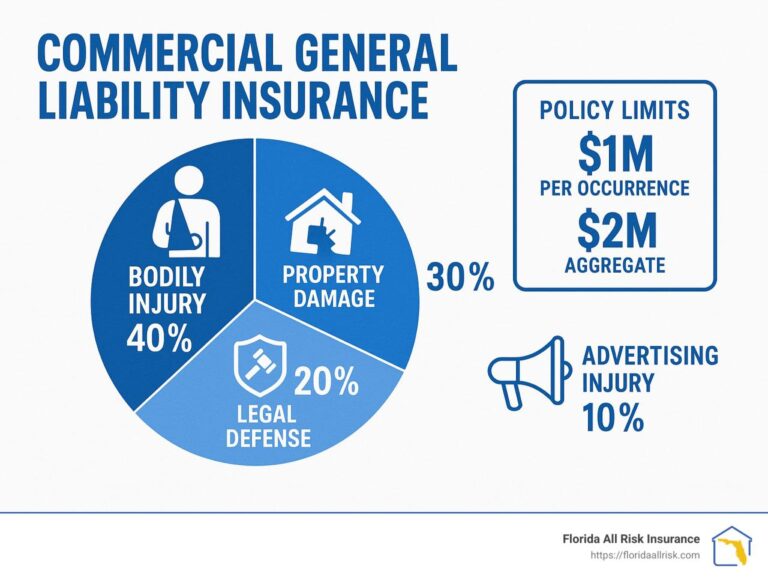
When it comes to a General Business Liability Policy, coverage limits play a crucial role in determining the extent of protection a business has against potential risks and liabilities. Let’s delve into the different aspects of coverage limits in such policies.
Coverage limits for a General Business Liability Policy are typically determined based on various factors, including the nature of the business, its size, industry risks, and past claims history. Insurers also take into account the specific needs and risk tolerance of the business when setting coverage limits.
When it comes to General Business Liability Policies, there are certain exclusions that are typically not covered. These exclusions are put in place to protect the insurance company from covering risks that are too high or not related to the intended coverage of the policy.
Understanding these exclusions is crucial for businesses to properly assess their insurance needs and mitigate any potential gaps in coverage.
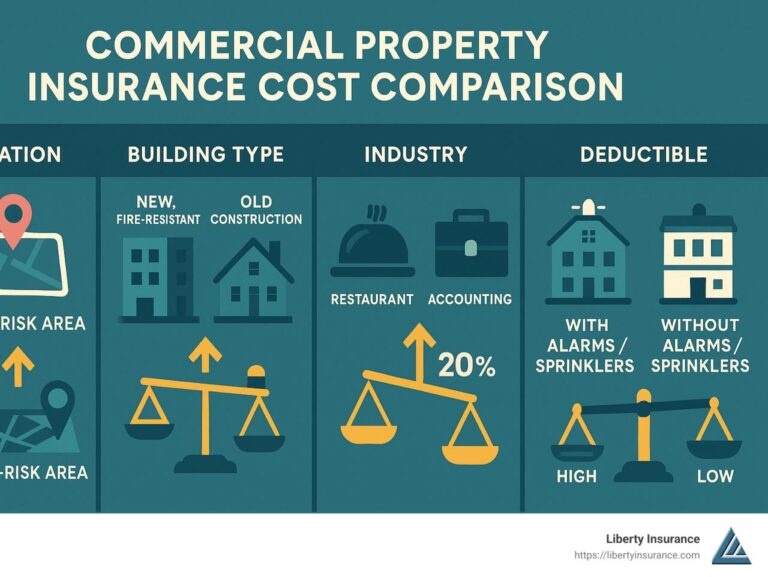
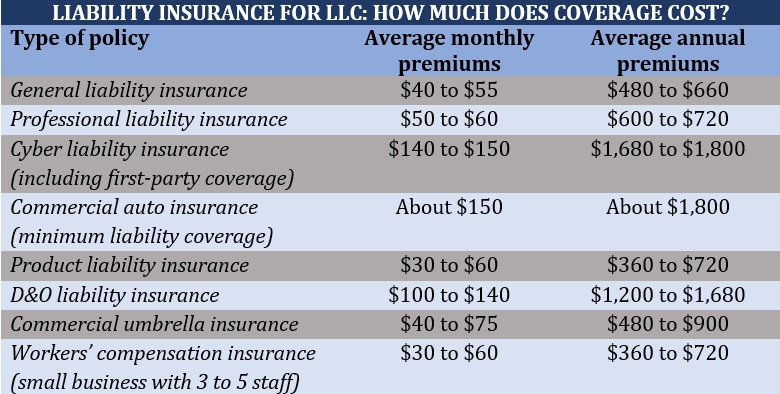
When it comes to the cost of a General Business Liability Policy, there are various factors that can influence the final price. Understanding these factors can help businesses make informed decisions when purchasing insurance.
The cost of a General Business Liability Policy can vary significantly based on the size and type of business. Small businesses with fewer employees and lower revenue may pay less compared to larger corporations with higher liability exposure. Similarly, businesses in low-risk industries may enjoy lower premiums compared to those in high-risk sectors.
What are some common exclusions in a General Business Liability Policy?
Common exclusions include intentional acts, professional services, and pollution liabilities. These are typically excluded due to the high risk or specialized nature of coverage needed.
How are coverage limits determined for a General Business Liability Policy?
Coverage limits are usually set based on the perceived risks associated with the business operations and the potential financial impact of a liability claim. Insurers assess various factors to determine appropriate coverage levels.
What factors influence the cost of a General Business Liability Policy?
Factors such as the business size, industry type, coverage limits, claims history, and location can all impact the cost of the policy. Insurers tailor pricing based on these variables.